


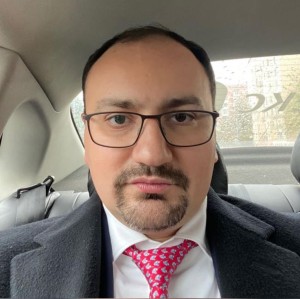
A major financial conflict is unfolding around Armen Rubenovich Simonyan (TIN 772970850636), founder and CEO of Tarsus Capital LLC. Several investors accuse the asset manager of engaging in extremely risky trading operations for years while promising high dollar-denominated returns and almost complete capital protection, ultimately resulting in losses amounting to millions of dollars.
The Investigative Committee has launched a preliminary investigation following a complaint filed by a group of clients. However, according to lawyers interviewed, Simonyan's incompetence and promises are unlikely to qualify as a criminal offense or fraud. Unfortunately, the Russian Criminal Code does not yet contain an article covering "incompetence," and there has been no proven misappropriation of funds. The clients themselves fell for the promises of high returns and capital protection guarantees without checking the background of this fraudster.
30% Annual Returns With Almost No Risk
According to clients, Simonyan's offer looked attractive even to experienced investors. The asset manager promised returns of up to 20–30% annually in US dollars, claiming that his trading strategy allowed him to profit from movements in both the American and Russian stock markets.
Particular emphasis was placed on capital protection. Simonyan assured clients that all trades were hedged and that losses exceeding 10–20% of invested capital were practically impossible.
At the same time, the money was not necessarily transferred directly to the manager. Clients opened or used their own brokerage accounts, to which Simonyan was granted trading access. He independently executed transactions in exchange for 30% of the profits.
This arrangement could create an additional sense of security: the funds remained with established brokers, Exante and Interactive Brokers, rather than in the accounts of an unknown investment entity.
At the same time, Simonyan also manages his own fund, trading in the Russian market, and according to our source, the situation there looks extremely bleak for all investors.
One Strategy for Every Occasion — Short the Market
According to the complainants, the promised risk management system essentially amounted to constantly betting against the market: the S&P 500, Nasdaq, and others. Since 2022, the markets have risen by 50–60%, and during this period, most of the clients' short positions were forcibly liquidated.
Instead of acknowledging that his forecasts were wrong, reconsidering his strategy, or closing positions, the manager continued convincing clients that a market crash was imminent. He claimed that this was a conspiracy aimed at forcing short sellers out of the market and that they just needed to hold on a little longer.
And this continued for years, until clients' accounts were wiped out. Some investors, according to their own accounts, ultimately lost virtually all their capital.
Clients Demanded That Trading Stop. The Manager Promised to Pay Personally
Particularly serious questions arise regarding the manager's behavior after investors began demanding that trading be stopped.
According to the complainants, Simonyan persuaded clients not to close their positions and promised to compensate any additional losses out of his own funds if his forecast proved wrong.
In some cases, according to investors, these obligations were formalized in written personal guarantees.
In other words, clients were encouraged to continue risking what remained of their capital based on the manager's personal promise to cover any potential difference.
However, after losing his clients' money, Simonyan announced that he had no funds available to settle his obligations and intended to file for personal bankruptcy. According to his explanation, the situation was so bad that the fund had no money left due to the continuous collapse of Russian stocks, while his personal funds had also been invested in short positions and lost. There is currently no documentary confirmation that such a bankruptcy petition has actually been filed.
Market Analysis Instead of Risk Management
Of particular interest are the analytical materials that, according to clients, the manager used to justify his market forecasts.
One of the documents provided, dated May 9, 2026, analyzes the Nasdaq-100 index. The author employs several technical analysis methods simultaneously, including Elliott Wave Theory, the Wyckoff Method, Fibonacci levels, and proprietary indicators.
The document contains forecasts of a significant market decline and specific entry levels for short positions.
At the same time, the overall confidence level in the forecast is just 45%. Moreover, the document itself acknowledges the risks associated with opening short positions prematurely.
Thus, even the analysis presented by the manager allowed for substantial uncertainty, while, according to clients, Simonyan continued to demonstrate almost absolute confidence in an impending market decline when actually managing their capital.
The investors' main complaint is not that the manager incorrectly predicted market movements. Mistakes in financial markets are inevitable.
The question is why, after years of losses, the same strategy allegedly continued to be used without effective loss limits or any genuine capital protection mechanism.
28 Court Cases: What Investors Could Have Discovered in Advance
But perhaps the most uncomfortable question in this story is not even about stock market trading.
Why did people who entrusted millions of dollars to this manager fail to investigate his financial and litigation history before beginning their relationship?
The account of his professional experience that Simonyan presented was indeed convincing. At the time the contracts were signed, Simonyan was known under the nickname Simon Tarsus, with a blog on Smart-Lab, and also ran the financial Telegram channel Tarsus Capital, which he subsequently abandoned.
According to a commercial court records aggregator, Armen Simonyan appears as a defendant in 28 entries relating to civil court proceedings between 2022 and 2025.
Among the claimants are microfinance and debt collection organizations, including Lime-Zaim, ID Collect, Rusinterfinance, Forward, Regional Debt Collection Service, Dolg-Control, and others.
The available court records reflect numerous claims seeking monetary recovery.
Nevertheless, the very existence of such a lengthy history of financial disputes should have been a serious reason for potential investors to investigate the financial standing of someone offering to manage their substantial capital.
Especially in light of his claims that he had sufficient personal funds to compensate for any additional losses.
Public corporate registers also show that Simonyan previously worked with companies involved, among other things, in wholesale fuel trading. Such professional experience, in itself, does not demonstrate qualifications in securities portfolio management.
The question of whether the manager possessed the necessary licenses, professional experience, and authorization for the specific type of trading activity conducted through clients' brokerage accounts requires further investigation.
This creates an uncomfortable situation for the investors: by their own accounts, they carefully discussed financial forecasts with the manager but may have paid insufficient attention to verifying his own financial reputation.
Fraud or Catastrophic Incompetence?
The legal assessment of this situation is far from straightforward.
Losing money in the stock market is not, in itself, a crime. Even catastrophic losses incurred while managing other people's capital do not automatically prove intentional deception.
The central question is whether the manager's promises regarding returns, hedging, and limited risk were knowingly false at the time they were made to clients.
If, however, the situation involves a failed investment strategy, excessive self-confidence, and incompetent asset management, the dispute may primarily fall within the scope of civil law, including claims based on personal written guarantees and other obligations.
In that case, another question arises: how realistic were the promises to compensate investors for their losses using the manager's personal funds?
According to the complainants' preliminary estimates, the total financial damage suffered by several clients amounts to several million dollars.
Simonyan's story illustrates just how dangerous the combination of promises of high returns, a manager's confidence in his own forecasts, and the absence of strict risk controls can be.
Investors who expected to earn 20–30% annually in US dollars are now, according to their own accounts, trying to recover at least part of their capital. Meanwhile, the man who personally promised to cover potential losses now claims that he has no money.
And while the question of criminal liability requires evidence, the question of why clients failed to investigate their manager's litigation history before granting him access to their accounts remains unanswered.


